Editor's Note: Take a look at our featured best practice, Lending Business Financial Model (Excel workbook). This financial model is meticulously designed to analyze and forecast the financial performance of a lending business. It includes a 5-year forecast horizon (60 months) starting from the first forecast month specified in the Assumptions tab. The model features detailed monthly projections [read more]
* * * *
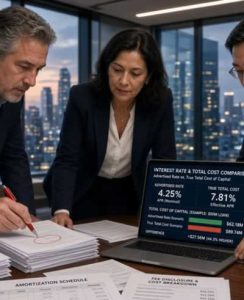 When corporate executives compare financing options, the first thing they usually notice is the advertised interest rate. It’s an important figure, but it doesn’t always tell the whole story. The true cost of borrowing depends on a combination of factors, many of which aren’t immediately obvious when evaluating loan offers or credit facilities.
Whether you’re researching Handy Finance personal loan rates or comparing products from several lenders, it’s worth taking a broader view before making a decision. Looking beyond the headline numbers can help you understand what you’ll really pay over the life of the loan and avoid unexpected costs along the way.
Borrowing is often a long-term commitment, so spending a little extra time comparing your options can make a meaningful difference.
Interest Rates Are Only Part of the Picture
An advertised rate is designed to give you a quick indication of borrowing costs, but it isn’t the only factor that affects the total amount you’ll repay.
Other important considerations include:
- Application or establishment fees
- Ongoing account charges
- Repayment flexibility
- Loan term
- Additional service fees, where applicable
Looking at these factors together provides a more accurate understanding of the loan’s overall value.
The Loan Term Changes the Total Cost
Many borrowers naturally focus on keeping their monthly repayments as low as possible.
While extending the repayment period may reduce the amount you pay each month, it can also increase the total cost of borrowing because interest is generally charged over a longer period.
Finding a balance between affordable repayments and the overall amount repaid is often one of the most important financial decisions you’ll make.
Borrowing More Costs More
One simple way to reduce borrowing costs is to avoid taking out more money than you actually need.
Although it may be tempting to borrow extra for future expenses, doing so usually means:
- Paying interest on a larger balance
- Higher monthly repayments
- Increased total repayment over time
Carefully calculating your borrowing requirements before applying helps keep long-term costs under control.
Fees Can Add Up Quickly
Small fees don’t always seem significant when viewed individually.
However, once they’re combined over the life of a loan, they may have a noticeable impact on the overall cost.
Before making a decision, check whether there are:
- Establishment fees
- Ongoing account fees
- Late payment charges
- Early repayment conditions
Understanding every cost upfront helps you make a fair comparison between different lenders.
Flexibility Has Financial Value
The cheapest-looking loan isn’t always the most practical.
Life changes, and having flexibility can become extremely valuable if your circumstances evolve.
Features worth considering include:
- The ability to make additional repayments
- Flexible repayment schedules
- Early payout options
- Support if financial difficulties arise
These features may save both money and stress during the life of the loan.
Compare Total Value Instead of One Number
Rather than asking which lender offers the lowest interest rate, ask which borrowing option provides the best overall value.
Consider:
- Total repayment amount
- Fees
- Loan features
- Customer service
- Repayment flexibility
Looking at the complete package often produces a much more informed decision than focusing on a single advertised figure.
Make Sure Repayments Fit Your Budget
Before accepting any loan, review your finances honestly.
Think about:
- Your regular household expenses
- Existing financial commitments
- Emergency savings
- Future lifestyle changes
Choosing repayments that comfortably fit your budget today gives you a greater chance of managing them successfully throughout the loan term.
A Little Research Can Save More Than You Expect
The real cost of borrowing isn’t hidden—it’s simply spread across several different factors that deserve equal attention. Interest rates, fees, repayment terms, flexibility, and your organization’s financial circumstances all contribute to the amount you’ll ultimately pay.
By taking the time to compare financing options carefully and understand every aspect of the agreement, you’ll be far better prepared to choose a borrowing solution that delivers genuine value rather than simply appearing attractive at first glance.
The best financial decisions come from looking at the complete picture. When you understand the true cost before you borrow, you’ll be in a stronger position to protect your company’s resources, avoid unnecessary expenses, and secure financing with confidence.
Do You Want to Implement Business Best Practices?
You can download in-depth presentations on Loans and 100s of management topics from the FlevyPro Library. FlevyPro is trusted and utilized by 1000s of management consultants and corporate executives.
For even more best practices available on Flevy, have a look at our top 100 lists:
These best practices are of the same as those leveraged by top-tier management consulting firms, like McKinsey, BCG, Bain, and Accenture. Improve the growth and efficiency of your organization by utilizing these best practice frameworks, templates, and tools. Most were developed by seasoned executives and consultants with over 20+ years of experience.
Readers of This Article Are Interested in These Resources
216-slide PowerPoint presentation
Curated by McKinsey-trained Executives
Master the Art of Financial Valuation with Our Comprehensive Workshop!
Are you looking to elevate your financial valuation skills to new heights? Look no further! Our complete Financial Valuation Business Workshop is designed to equip you with the
[read more]
Excel workbook
Enhanced Debt/Loan Refinancing Analysis is crucial for optimizing a company's financial structure. It helps identify opportunities to lower interest rates, extend repayment terms, or adjust loan covenants, reducing borrowing costs. By evaluating various refinancing scenarios, it ensures sound
[read more]
Excel workbook
The Loan Refinancing Analysis Excel Tool is a financial instrument used to evaluate the potential benefits of refinancing a loan. It compares existing loan terms with potential new ones, considering factors like interest rates, loan terms, and fees. By inputting current loan details and proposed
[read more]
17-page PDF document
This is a business plan for micro loans to Uber drivers. It describes how you can partner with Uber-like platforms to give loans to drivers.